NCST — Clinical trial insurance policy, revised December 2012 — National Policy Requirement and Guidance for the Provision of Insurance Cover for Research Participants in Clinical Trials in Malawi — Revised Second Edition
Currentness under review. Whether this instrument remains applicable is under review. Consult the later instruments and source context below before relying on it.
Link directly to a passage with its anchor — for example #pdf-page-1 — to open it highlighted. This reference version is generated from the authority’s publication and does not replace it. Language: English.
Contents
NATIONAL POLICY REQUIREMENT AND
GUIDANCE FOR THE PROVISION OF
INSURANCE COVER FOR RESEARCH
PARTICIPANTS IN CLINICAL TRIALS IN
MALAWI
[Sections 18 & 48 of the S&T Act No.16 of 2003]
National Commission for Science and
Technology
Revised 2nd Edition
December, 2012
malawi-clinical-trial-insurance-policy-2012 — official PDF page 1; original table columns, symbols and diagram connections
National Commission for Science and Technology
Lingadzi House, City Centre
Private Bag B303
LILONGWE 3, Malawi
Tel: 265 1771 550
Fax: 265 1772 431
E-mail: directorgeneral@ncst.mw
Website: www.ncst.mw
Secretariat Address for the Operations of the National Health Sciences
Research Committee:
The Chairman
National Health Sciences Research Committee
C/O Ministry of Health
Research Unit
P.O. Box 30377
Capital City
LILONGWE 3
Malawi
Tel: 265 1 789 400,789 321
E-mail: doccentre@malawi.net
malawi-clinical-trial-insurance-policy-2012 — official PDF page 2; original table columns, symbols and diagram connections
ACKNOWLEDGEMENT
The 2012 revised edition of the National Policy Requirement and Guidance for the
Provision of Insurance Cover for Research Participants in Clinical Trials in Malawi
builds on the first edition of 2008. In pursuance of its legal mandate as enshrined in
sections 18 and 48 of the Science and Technology Act No 16 of 2003, the development
of this revised edition was undertaken by the National Commission for Science and
Technology (NCST). This edition is the product of the NCST’s consultation of a cross-
section of stakeholders. The NCST would like to gratefully acknowledge the efforts of all
manner of people that were engaged at different stages of the development process.
Specifically, I would like to pay special tribute to the following;
• National Health Sciences Research Committee (NHSRC) and National
Committee on Bioethics (NACOB) which in line with their specific terms of
reference as technical functional committees of NCST were structures through
which this edition was developed. Members of the committees under the
committed leadership and guidance of Dr Charles C V Mwansambo and Prof
Joseph Mfutso-Bengo, respectively, worked tirelessly in collaboration with the
secretariat to develop this revised edition;
• Representatives of the Insurance Industry who assisted a great deal in
providing the much needed professional advice and information that has all been
duly incorporated into this policy requirement;
• Prof Carl H. Coleman, Professor of Health Law and Director of Global Initiatives
at the Centre for Health and Pharmaceutical Law and Policy at Seton Hall
University in USA, and Consultant for World Health Organisation, who kindly
contributed to the development of this edition by providing very constructive
comments and insights; and
• All stakeholders who constructively critiqued the entire policy document by
providing very useful comments.
Sponsors, researchers and all other stakeholders are, therefore, called upon to adhere
to this revised policy requirement and guidance for the provision of insurance cover for
research participants in clinical trials in Malawi. The adherence to this requirement will
not only foster the desired protection for research participants but will also enhance
speedy review and approval of clinical trials planned to be conducted in Malawi.
Dr H M Chimoyo
DIRECTOR GENERAL
NATIONAL COMMISSION FOR SCIENCE AND TECHNOLOGY
i
malawi-clinical-trial-insurance-policy-2012 — official PDF page 3; original table columns, symbols and diagram connections
Table of Contents
ACKNOWLEDGEMENT ................................................................................................... i
1.0 INTRODUCTION..................................................................................................... 1
2.0 TYPE AND SCOPE OF THE REQUIRED INSURANCE COVER ........................... 2
3.0 PERIOD OF INSURANCE COVERAGE AND COMPENSATION ........................... 3
4.0 OBTAINING THE INSURANCE COVER OF NO-FAULT TYPE ............................. 4
5.0 AUNTHETICITY OF THE INSURANCE COVER DOCUMENTS ............................ 5
6.0 GOVERNING POLICY AND LAW ........................................................................... 5
7.0 ELEMENTS OF REVIEW OF SUBMITTED INSURANCE DOCUMENTS .............. 6
8.0 POLICY EXCLUSIONS FROM THIS REQUIREMENT ........................................... 7
9.0 CONCLUSION ........................................................................................................ 8
ii
malawi-clinical-trial-insurance-policy-2012 — official PDF page 4; original table columns, symbols and diagram connections
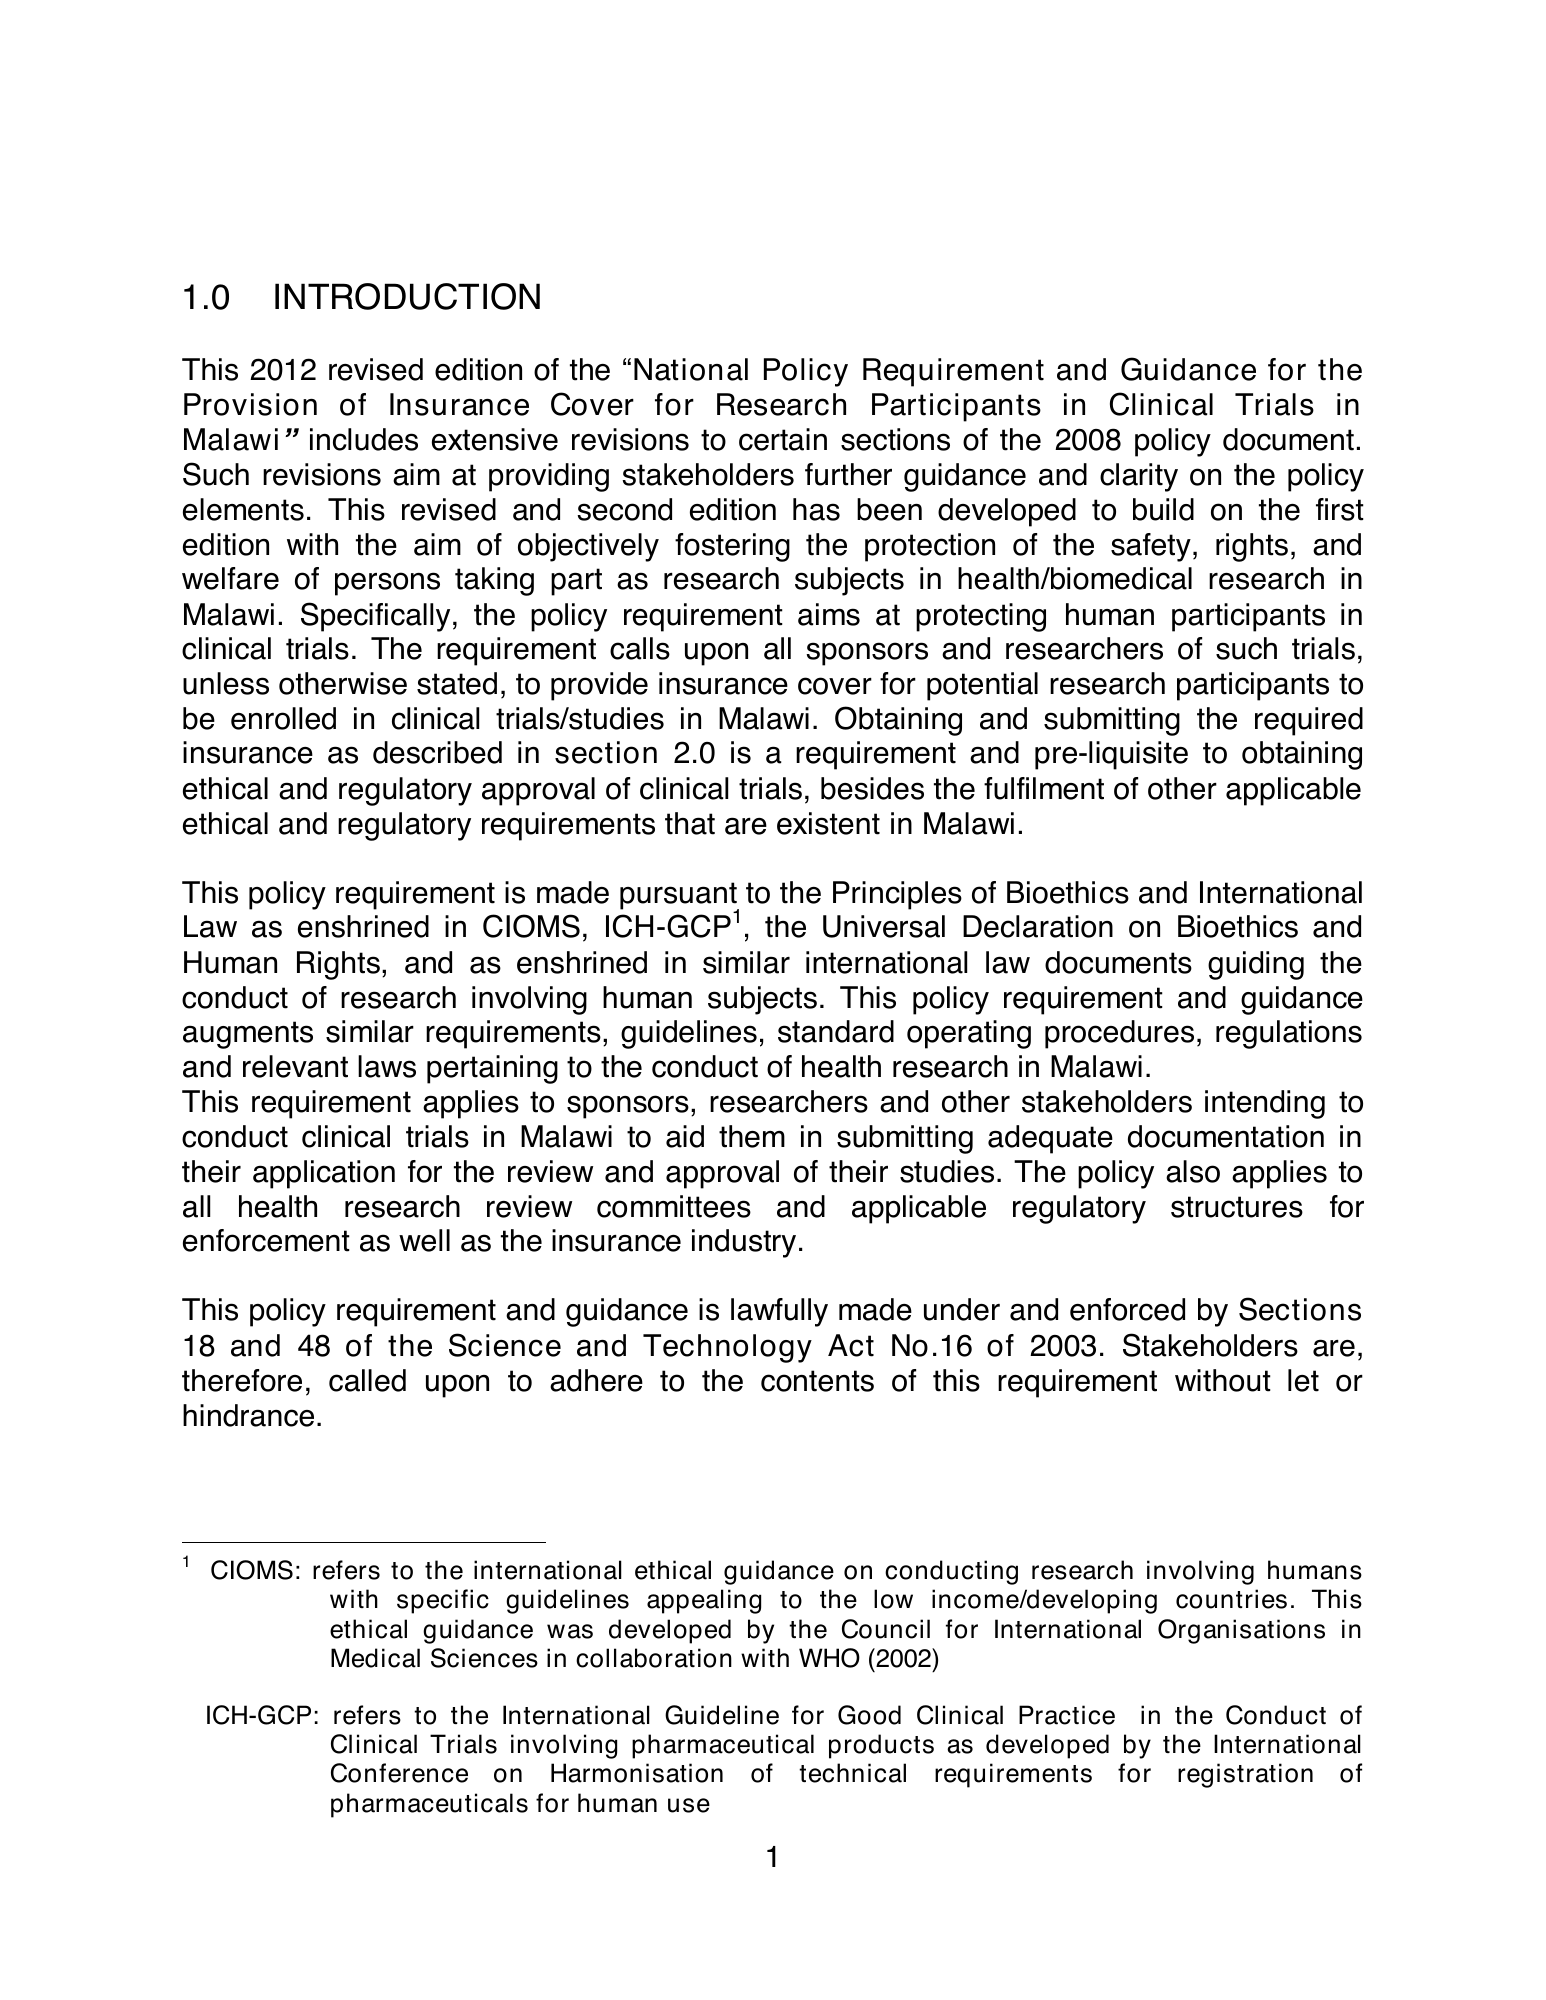
1.0 INTRODUCTION
This 2012 revised edition of the “National Policy Requirement and Guidance for the
Provision of Insurance Cover for Research Participants in Clinical Trials in
Malawi” includes extensive revisions to certain sections of the 2008 policy document.
Such revisions aim at providing stakeholders further guidance and clarity on the policy
elements. This revised and second edition has been developed to build on the first
edition with the aim of objectively fostering the protection of the safety, rights, and
welfare of persons taking part as research subjects in health/biomedical research in
Malawi. Specifically, the policy requirement aims at protecting human participants in
clinical trials. The requirement calls upon all sponsors and researchers of such trials,
unless otherwise stated, to provide insurance cover for potential research participants to
be enrolled in clinical trials/studies in Malawi. Obtaining and submitting the required
insurance as described in section 2.0 is a requirement and pre-liquisite to obtaining
ethical and regulatory approval of clinical trials, besides the fulfilment of other applicable
ethical and regulatory requirements that are existent in Malawi.
This policy requirement is made pursuant to the Principles of Bioethics and International
Law as enshrined in CIOMS, ICH-GCP1, the Universal Declaration on Bioethics and
Human Rights, and as enshrined in similar international law documents guiding the
conduct of research involving human subjects. This policy requirement and guidance
augments similar requirements, guidelines, standard operating procedures, regulations
and relevant laws pertaining to the conduct of health research in Malawi.
This requirement applies to sponsors, researchers and other stakeholders intending to
conduct clinical trials in Malawi to aid them in submitting adequate documentation in
their application for the review and approval of their studies. The policy also applies to
all health research review committees and applicable regulatory structures for
enforcement as well as the insurance industry.
This policy requirement and guidance is lawfully made under and enforced by Sections
18 and 48 of the Science and Technology Act No.16 of 2003. Stakeholders are,
therefore, called upon to adhere to the contents of this requirement without let or
hindrance.
1
CIOMS: refers to the international ethical guidance on conducting research involving humans
with specific guidelines appealing to the low income/developing countries. This
ethical guidance was developed by the Council for International Organisations in
Medical Sciences in collaboration with WHO (2002)
ICH-GCP: refers to the International Guideline for Good Clinical Practice in the Conduct of
Clinical Trials involving pharmaceutical products as developed by the International
Conference on Harmonisation of technical requirements for registration of
pharmaceuticals for human use
1
malawi-clinical-trial-insurance-policy-2012 — official PDF page 5; original table columns, symbols and diagram connections
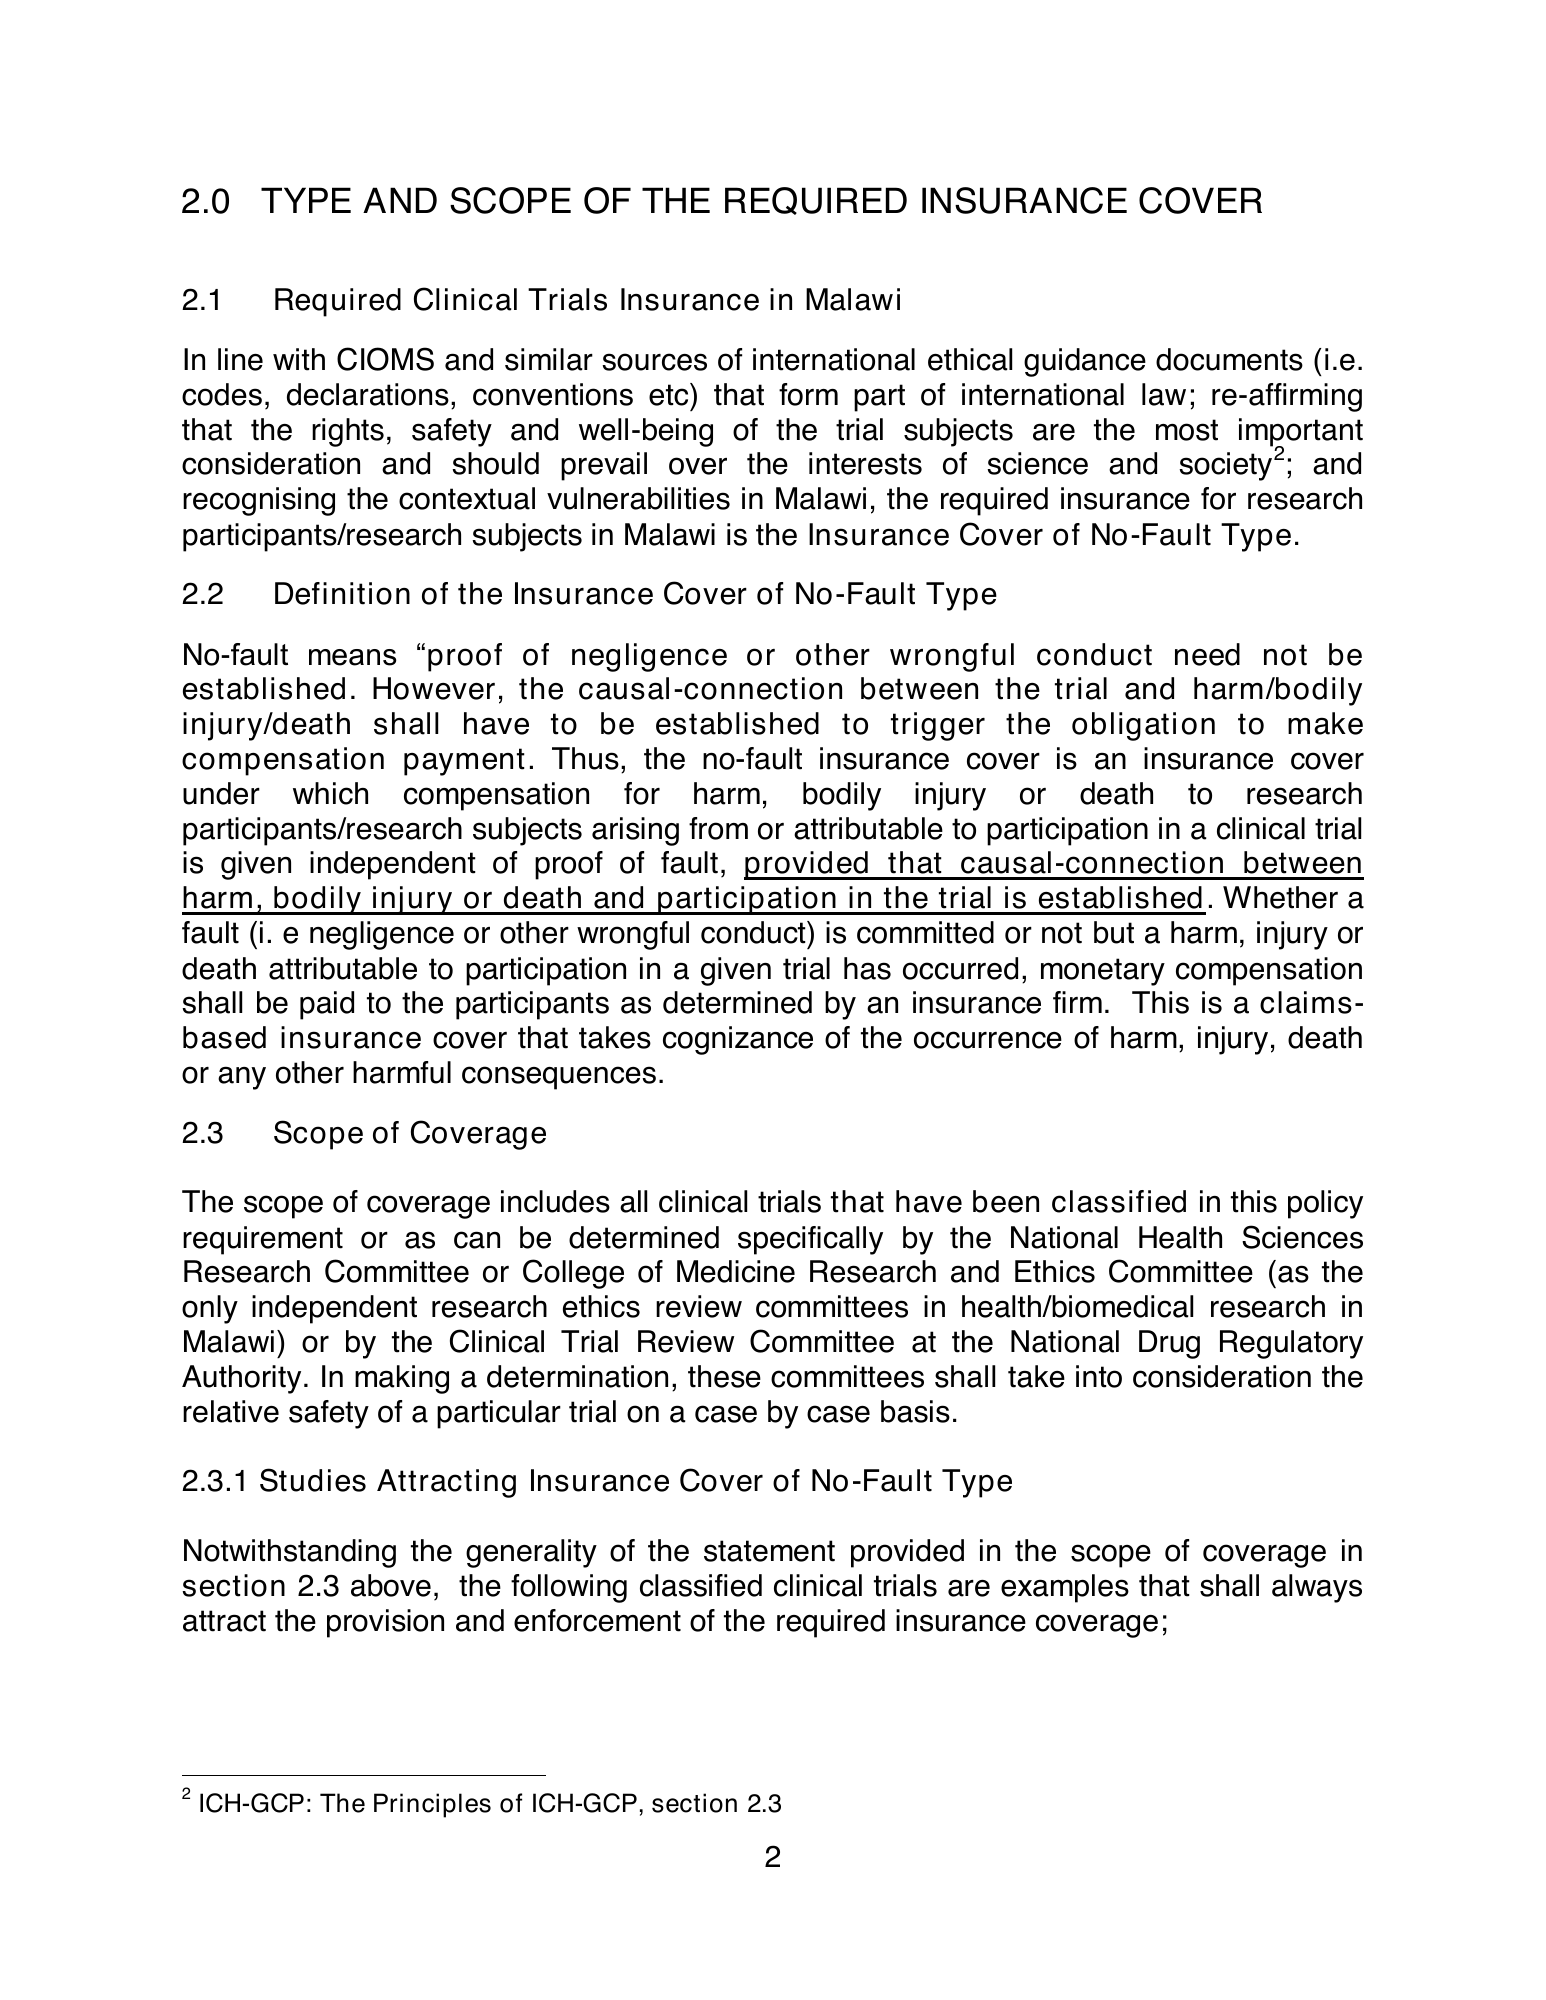
2.0 TYPE AND SCOPE OF THE REQUIRED INSURANCE COVER
2.1 Required Clinical Trials Insurance in Malawi
In line with CIOMS and similar sources of international ethical guidance documents (i.e.
codes, declarations, conventions etc) that form part of international law; re-affirming
that the rights, safety and well-being of the trial subjects are the most important
consideration and should prevail over the interests of science and society 2; and
recognising the contextual vulnerabilities in Malawi, the required insurance for research
participants/research subjects in Malawi is the Insurance Cover of No-Fault Type.
2.2 Definition of the Insurance Cover of No-Fault Type
No-fault means “proof of negligence or other wrongful conduct need not be
established. However, the causal-connection between the trial and harm/bodily
injury/death shall have to be established to trigger the obligation to make
compensation payment. Thus, the no-fault insurance cover is an insurance cover
under which compensation for harm, bodily injury or death to research
participants/research subjects arising from or attributable to participation in a clinical trial
is given independent of proof of fault, provided that causal-connection between
harm, bodily injury or death and participation in the trial is established. Whether a
fault (i. e negligence or other wrongful conduct) is committed or not but a harm, injury or
death attributable to participation in a given trial has occurred, monetary compensation
shall be paid to the participants as determined by an insurance firm. This is a claims-
based insurance cover that takes cognizance of the occurrence of harm, injury, death
or any other harmful consequences.
2.3 Scope of Coverage
The scope of coverage includes all clinical trials that have been classified in this policy
requirement or as can be determined specifically by the National Health Sciences
Research Committee or College of Medicine Research and Ethics Committee (as the
only independent research ethics review committees in health/biomedical research in
Malawi) or by the Clinical Trial Review Committee at the National Drug Regulatory
Authority. In making a determination, these committees shall take into consideration the
relative safety of a particular trial on a case by case basis.
2.3.1 Studies Attracting Insurance Cover of No-Fault Type
Notwithstanding the generality of the statement provided in the scope of coverage in
section 2.3 above, the following classified clinical trials are examples that shall always
attract the provision and enforcement of the required insurance coverage;
2
ICH-GCP: The Principles of ICH-GCP, section 2.3
2
malawi-clinical-trial-insurance-policy-2012 — official PDF page 6; original table columns, symbols and diagram connections
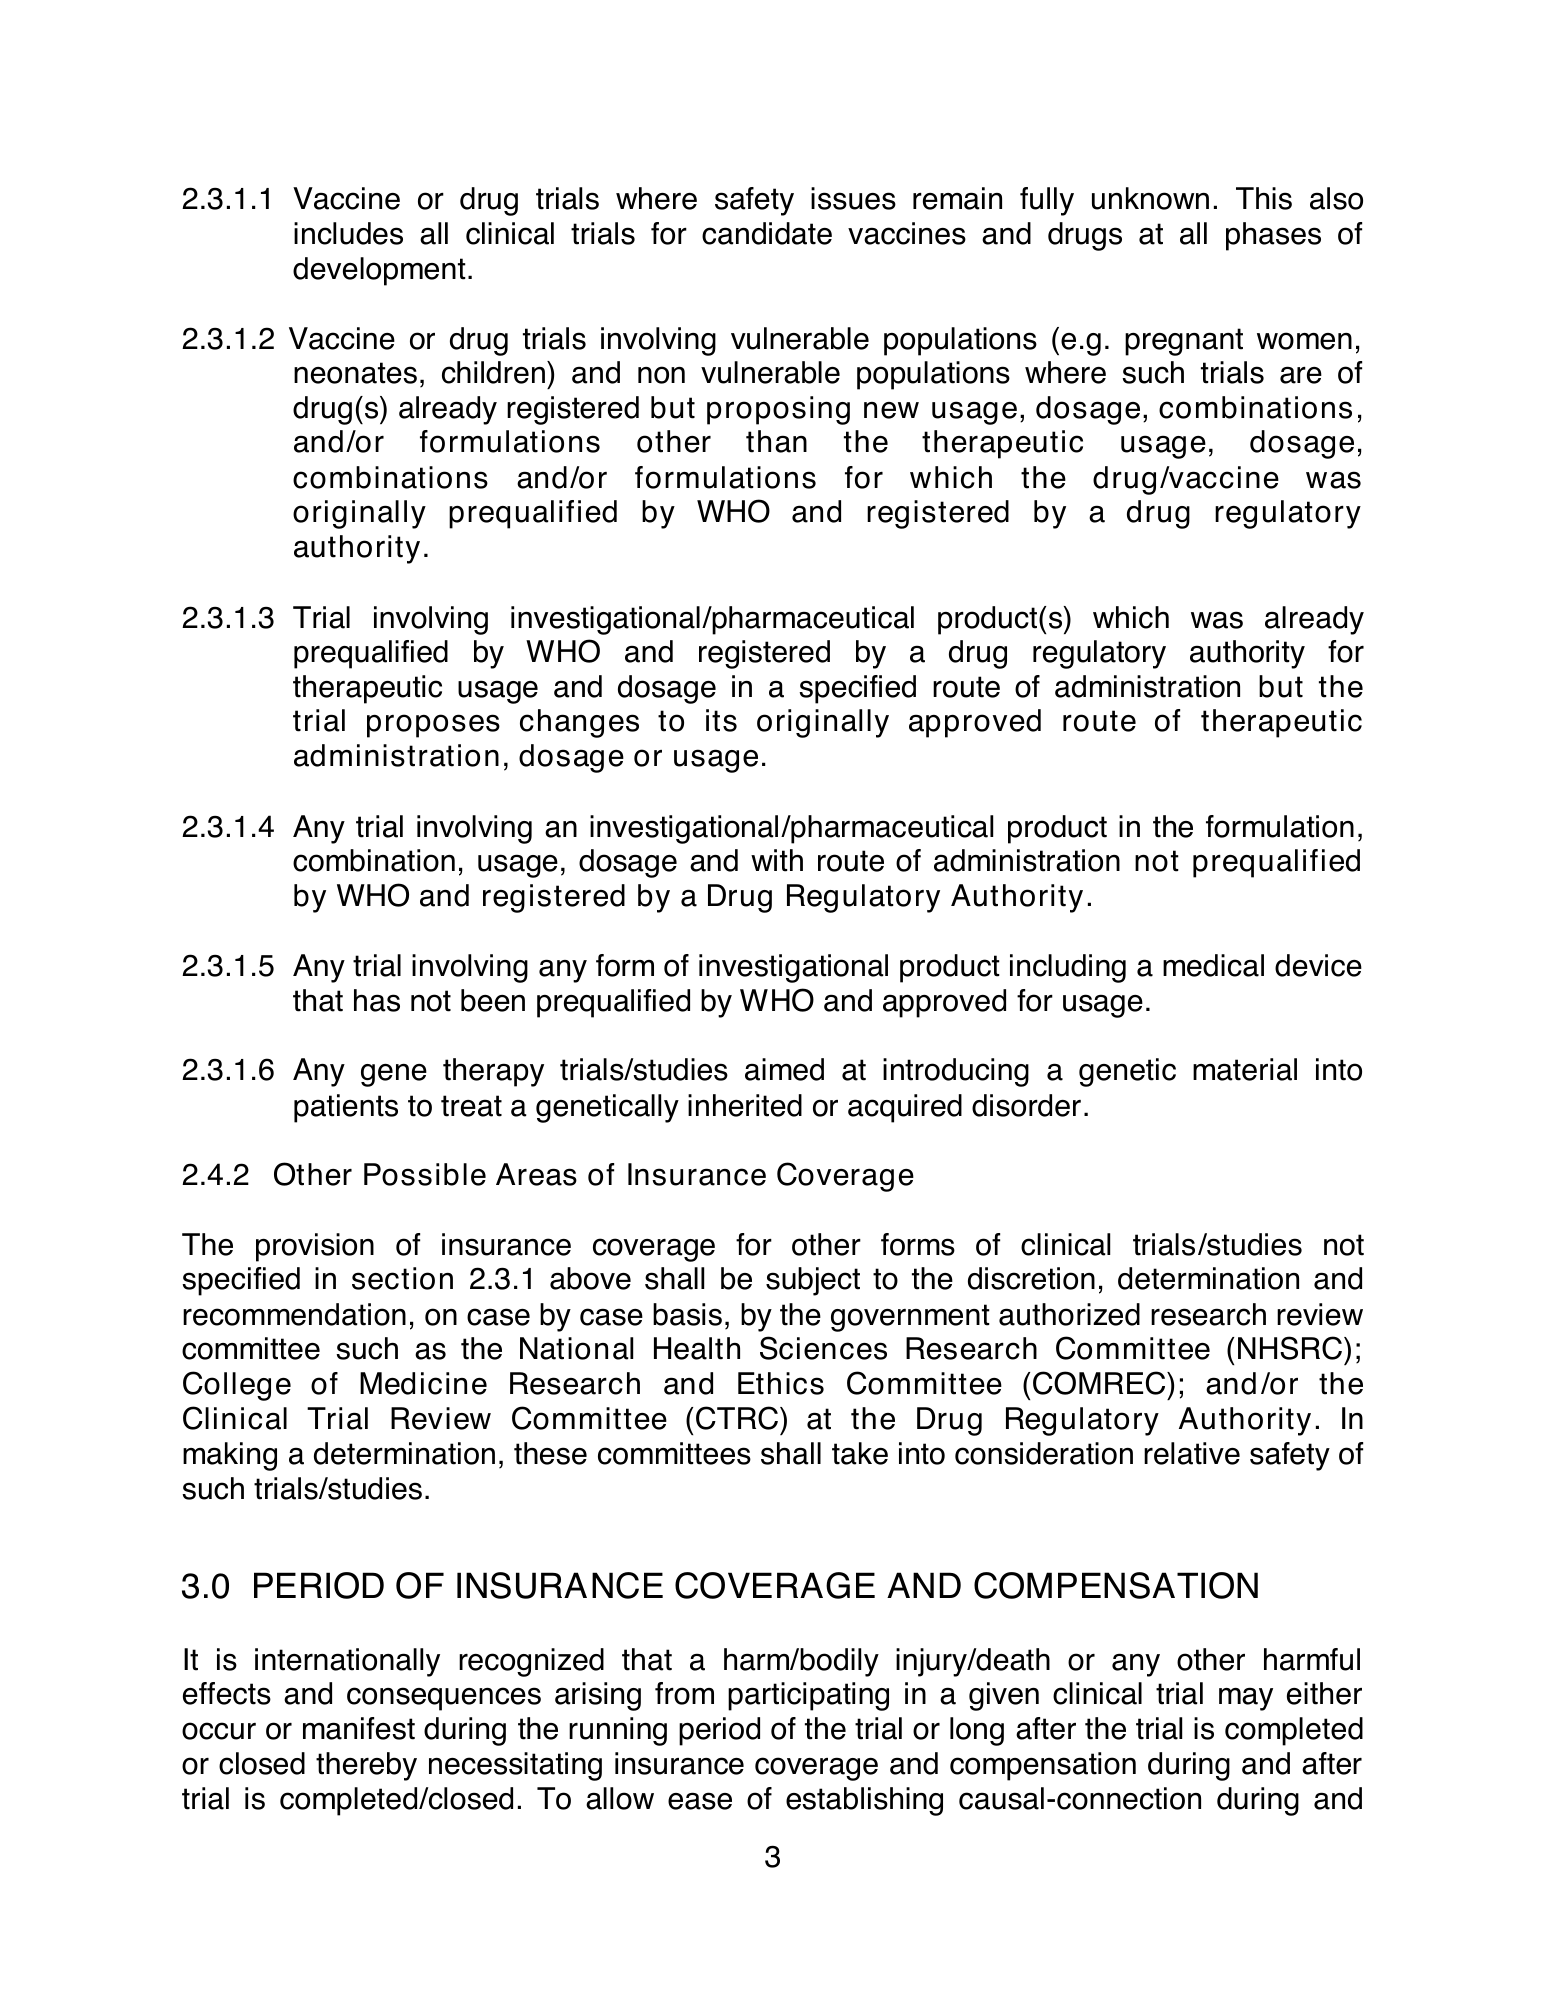
2.3.1.1 Vaccine or drug trials where safety issues remain fully unknown. This also
includes all clinical trials for candidate vaccines and drugs at all phases of
development.
2.3.1.2 Vaccine or drug trials involving vulnerable populations (e.g. pregnant women,
neonates, children) and non vulnerable populations where such trials are of
drug(s) already registered but proposing new usage, dosage, combinations,
and/or formulations other than the therapeutic usage, dosage,
combinations and/or formulations for which the drug/vaccine was
originally prequalified by WHO and registered by a drug regulatory
authority.
2.3.1.3 Trial involving investigational/pharmaceutical product(s) which was already
prequalified by WHO and registered by a drug regulatory authority for
therapeutic usage and dosage in a specified route of administration but the
trial proposes changes to its originally approved route of therapeutic
administration, dosage or usage.
2.3.1.4 Any trial involving an investigational/pharmaceutical product in the formulation,
combination, usage, dosage and with route of administration not prequalified
by WHO and registered by a Drug Regulatory Authority.
2.3.1.5 Any trial involving any form of investigational product including a medical device
that has not been prequalified by WHO and approved for usage.
2.3.1.6 Any gene therapy trials/studies aimed at introducing a genetic material into
patients to treat a genetically inherited or acquired disorder.
2.4.2 Other Possible Areas of Insurance Coverage
The provision of insurance coverage for other forms of clinical trials/studies not
specified in section 2.3.1 above shall be subject to the discretion, determination and
recommendation, on case by case basis, by the government authorized research review
committee such as the National Health Sciences Research Committee (NHSRC);
College of Medicine Research and Ethics Committee (COMREC); and/or the
Clinical Trial Review Committee (CTRC) at the Drug Regulatory Authority. In
making a determination, these committees shall take into consideration relative safety of
such trials/studies.
3.0 PERIOD OF INSURANCE COVERAGE AND COMPENSATION
It is internationally recognized that a harm/bodily injury/death or any other harmful
effects and consequences arising from participating in a given clinical trial may either
occur or manifest during the running period of the trial or long after the trial is completed
or closed thereby necessitating insurance coverage and compensation during and after
trial is completed/closed. To allow ease of establishing causal-connection during and
3
malawi-clinical-trial-insurance-policy-2012 — official PDF page 7; original table columns, symbols and diagram connections
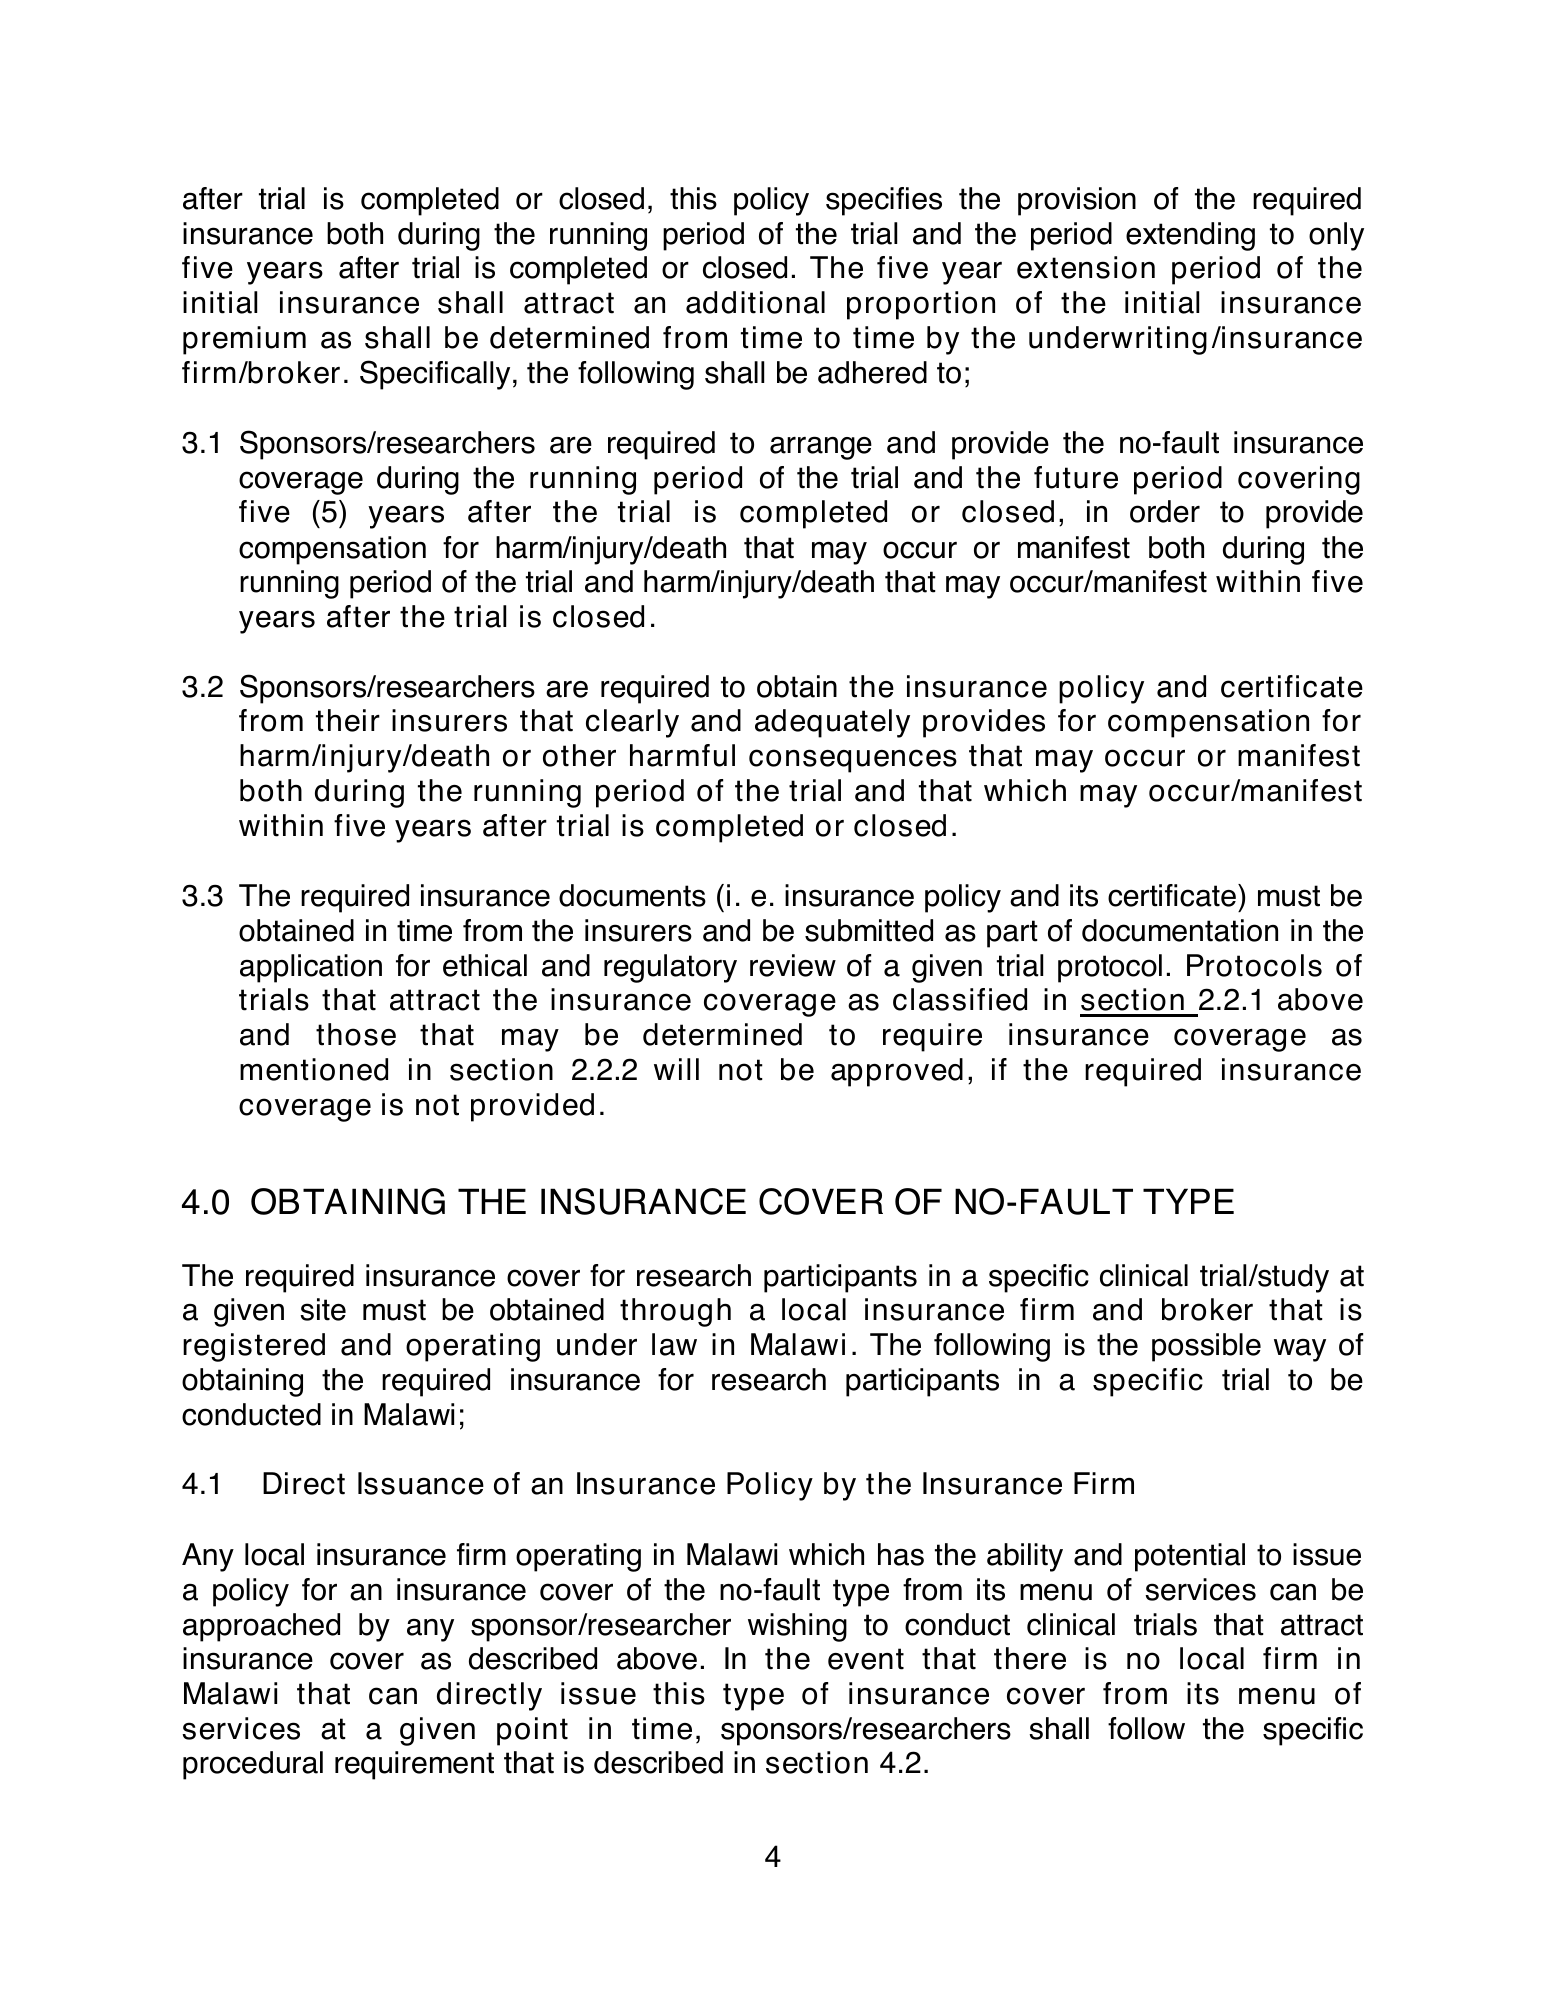
after trial is completed or closed, this policy specifies the provision of the required
insurance both during the running period of the trial and the period extending to only
five years after trial is completed or closed. The five year extension period of the
initial insurance shall attract an additional proportion of the initial insurance
premium as shall be determined from time to time by the underwriting/insurance
firm/broker. Specifically, the following shall be adhered to;
3.1 Sponsors/researchers are required to arrange and provide the no-fault insurance
coverage during the running period of the trial and the future period covering
five (5) years after the trial is completed or closed, in order to provide
compensation for harm/injury/death that may occur or manifest both during the
running period of the trial and harm/injury/death that may occur/manifest within five
years after the trial is closed.
3.2 Sponsors/researchers are required to obtain the insurance policy and certificate
from their insurers that clearly and adequately provides for compensation for
harm/injury/death or other harmful consequences that may occur or manifest
both during the running period of the trial and that which may occur/manifest
within five years after trial is completed or closed.
3.3 The required insurance documents (i. e. insurance policy and its certificate) must be
obtained in time from the insurers and be submitted as part of documentation in the
application for ethical and regulatory review of a given trial protocol. Protocols of
trials that attract the insurance coverage as classified in section 2.2.1 above
and those that may be determined to require insurance coverage as
mentioned in section 2.2.2 will not be approved, if the required insurance
coverage is not provided.
4.0 OBTAINING THE INSURANCE COVER OF NO-FAULT TYPE
The required insurance cover for research participants in a specific clinical trial/study at
a given site must be obtained through a local insurance firm and broker that is
registered and operating under law in Malawi. The following is the possible way of
obtaining the required insurance for research participants in a specific trial to be
conducted in Malawi;
4.1 Direct Issuance of an Insurance Policy by the Insurance Firm
Any local insurance firm operating in Malawi which has the ability and potential to issue
a policy for an insurance cover of the no-fault type from its menu of services can be
approached by any sponsor/researcher wishing to conduct clinical trials that attract
insurance cover as described above. In the event that there is no local firm in
Malawi that can directly issue this type of insurance cover from its menu of
services at a given point in time, sponsors/researchers shall follow the specific
procedural requirement that is described in section 4.2.
4
malawi-clinical-trial-insurance-policy-2012 — official PDF page 8; original table columns, symbols and diagram connections
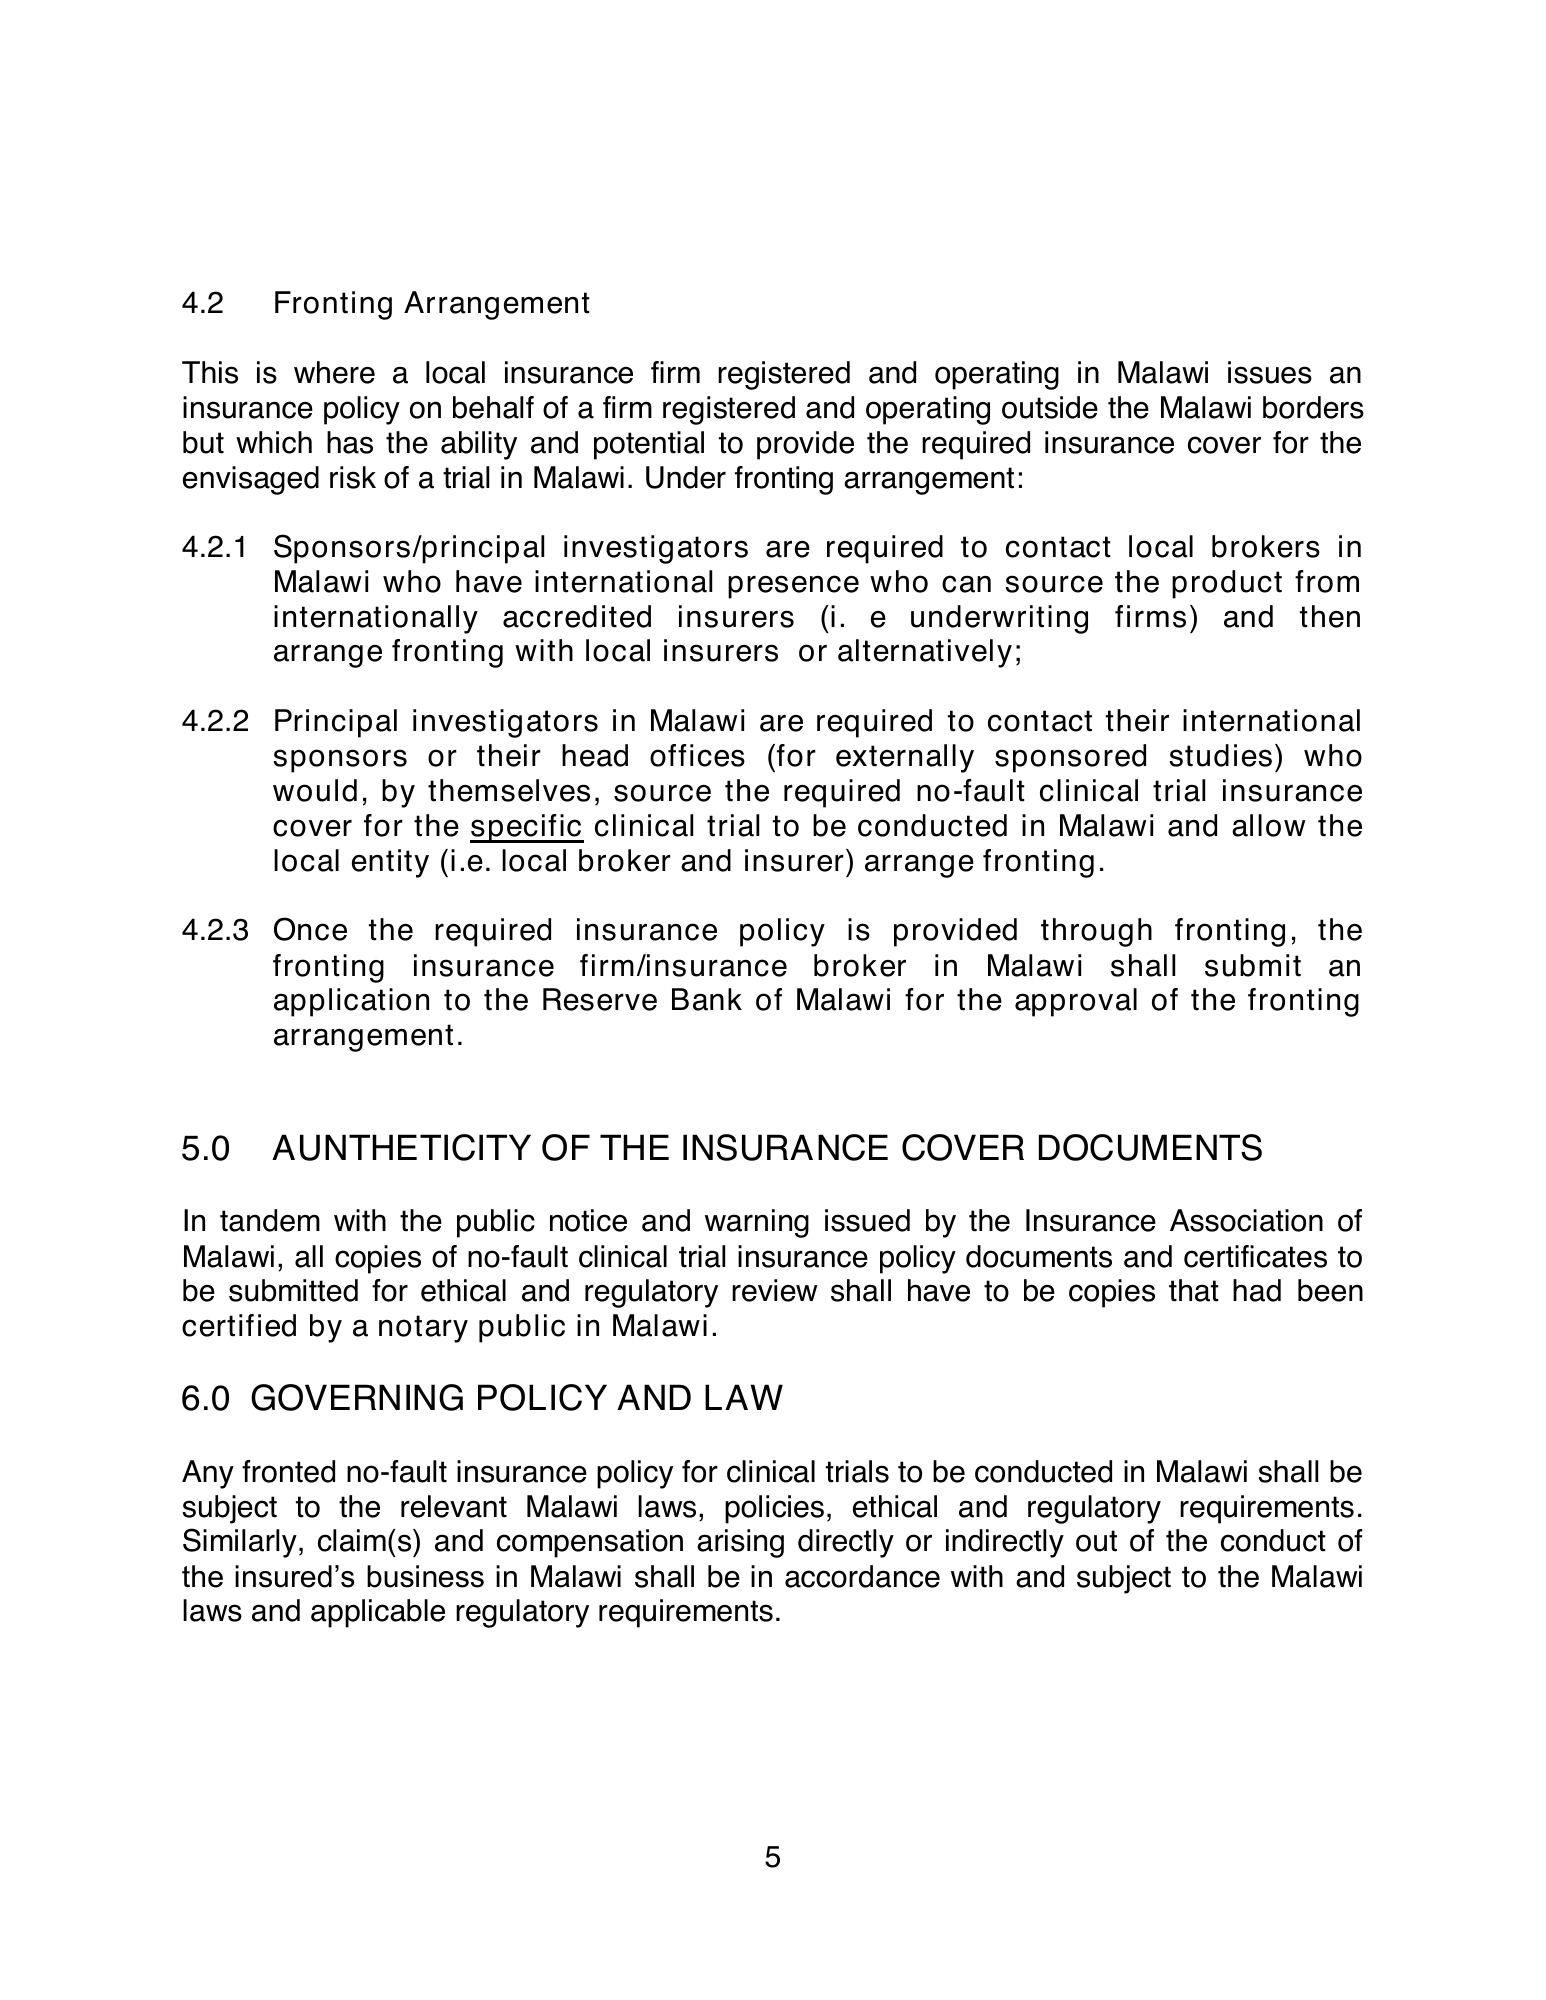
4.2 Fronting Arrangement
This is where a local insurance firm registered and operating in Malawi issues an
insurance policy on behalf of a firm registered and operating outside the Malawi borders
but which has the ability and potential to provide the required insurance cover for the
envisaged risk of a trial in Malawi. Under fronting arrangement:
4.2.1 Sponsors/principal investigators are required to contact local brokers in
Malawi who have international presence who can source the product from
internationally accredited insurers (i. e underwriting firms) and then
arrange fronting with local insurers or alternatively;
4.2.2 Principal investigators in Malawi are required to contact their international
sponsors or their head offices (for externally sponsored studies) who
would, by themselves, source the required no-fault clinical trial insurance
cover for the specific clinical trial to be conducted in Malawi and allow the
local entity (i.e. local broker and insurer) arrange fronting.
4.2.3 Once the required insurance policy is provided through fronting, the
fronting insurance firm/insurance broker in Malawi shall submit an
application to the Reserve Bank of Malawi for the approval of the fronting
arrangement.
5.0 AUNTHETICITY OF THE INSURANCE COVER DOCUMENTS
In tandem with the public notice and warning issued by the Insurance Association of
Malawi, all copies of no-fault clinical trial insurance policy documents and certificates to
be submitted for ethical and regulatory review shall have to be copies that had been
certified by a notary public in Malawi.
6.0 GOVERNING POLICY AND LAW
Any fronted no-fault insurance policy for clinical trials to be conducted in Malawi shall be
subject to the relevant Malawi laws, policies, ethical and regulatory requirements.
Similarly, claim(s) and compensation arising directly or indirectly out of the conduct of
the insured’s business in Malawi shall be in accordance with and subject to the Malawi
laws and applicable regulatory requirements.
5
malawi-clinical-trial-insurance-policy-2012 — official PDF page 9; original table columns, symbols and diagram connections
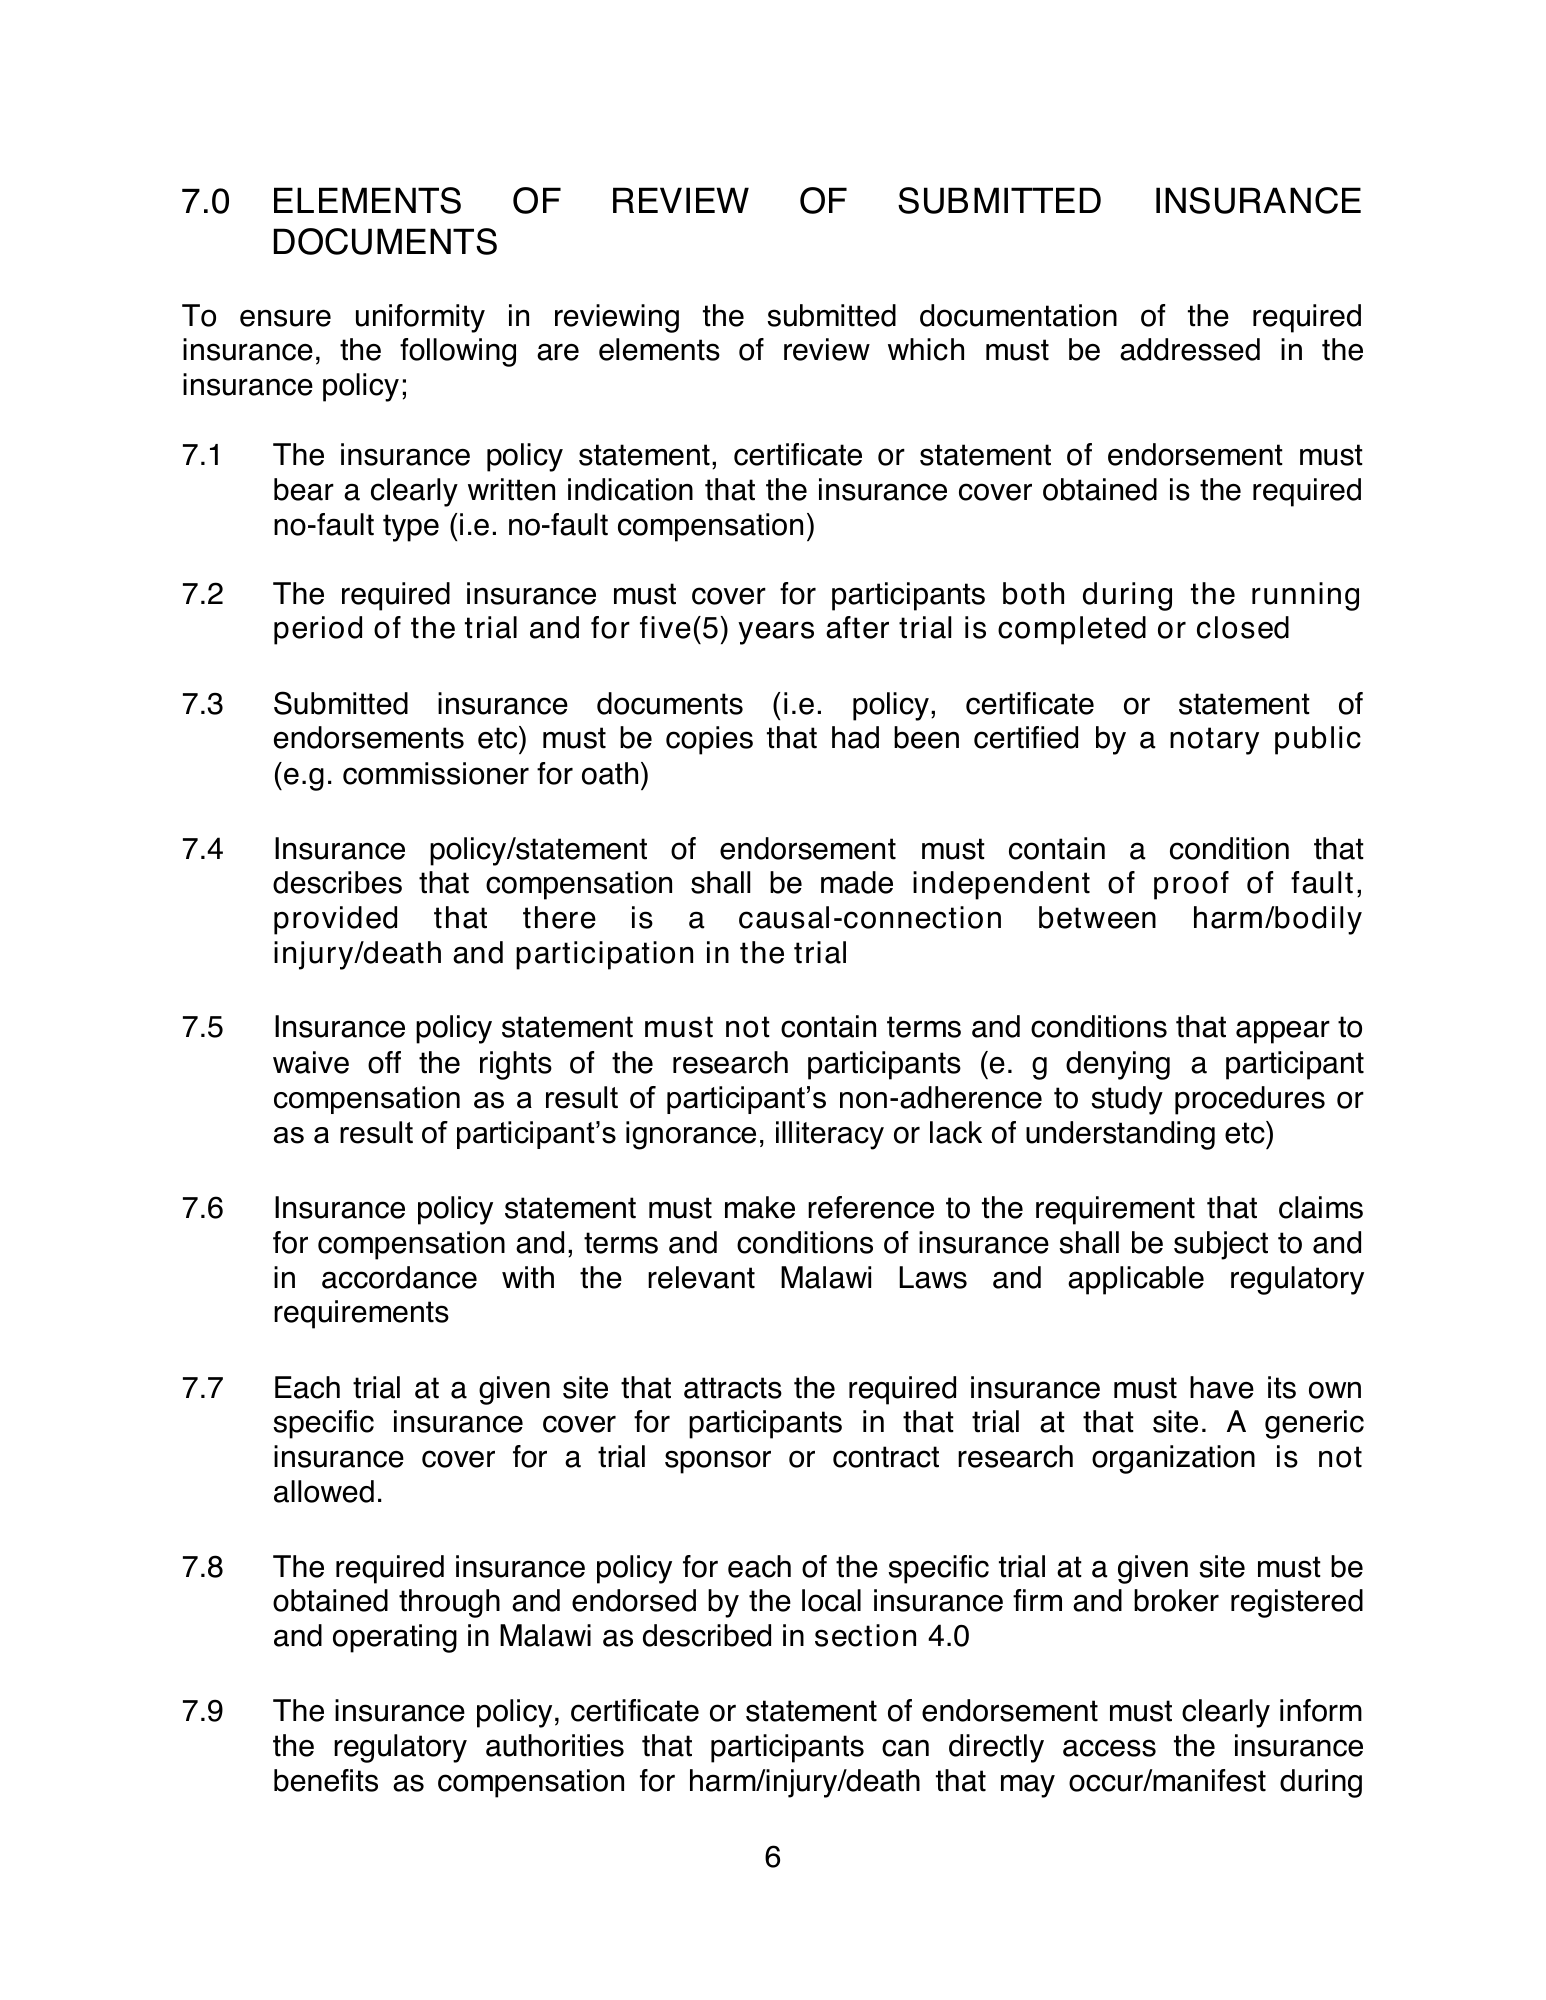
7.0 ELEMENTS OF REVIEW OF SUBMITTED INSURANCE
DOCUMENTS
To ensure uniformity in reviewing the submitted documentation of the required
insurance, the following are elements of review which must be addressed in the
insurance policy;
7.1 The insurance policy statement, certificate or statement of endorsement must
bear a clearly written indication that the insurance cover obtained is the required
no-fault type (i.e. no-fault compensation)
7.2 The required insurance must cover for participants both during the running
period of the trial and for five(5) years after trial is completed or closed
7.3 Submitted insurance documents (i.e. policy, certificate or statement of
endorsements etc) must be copies that had been certified by a notary public
(e.g. commissioner for oath)
7.4 Insurance policy/statement of endorsement must contain a condition that
describes that compensation shall be made independent of proof of fault,
provided that there is a causal-connection between harm/bodily
injury/death and participation in the trial
7.5 Insurance policy statement must not contain terms and conditions that appear to
waive off the rights of the research participants (e. g denying a participant
compensation as a result of participant’s non-adherence to study procedures or
as a result of participant’s ignorance, illiteracy or lack of understanding etc)
7.6 Insurance policy statement must make reference to the requirement that claims
for compensation and, terms and conditions of insurance shall be subject to and
in accordance with the relevant Malawi Laws and applicable regulatory
requirements
7.7 Each trial at a given site that attracts the required insurance must have its own
specific insurance cover for participants in that trial at that site. A generic
insurance cover for a trial sponsor or contract research organization is not
allowed.
7.8 The required insurance policy for each of the specific trial at a given site must be
obtained through and endorsed by the local insurance firm and broker registered
and operating in Malawi as described in section 4.0
7.9 The insurance policy, certificate or statement of endorsement must clearly inform
the regulatory authorities that participants can directly access the insurance
benefits as compensation for harm/injury/death that may occur/manifest during
6
malawi-clinical-trial-insurance-policy-2012 — official PDF page 10; original table columns, symbols and diagram connections
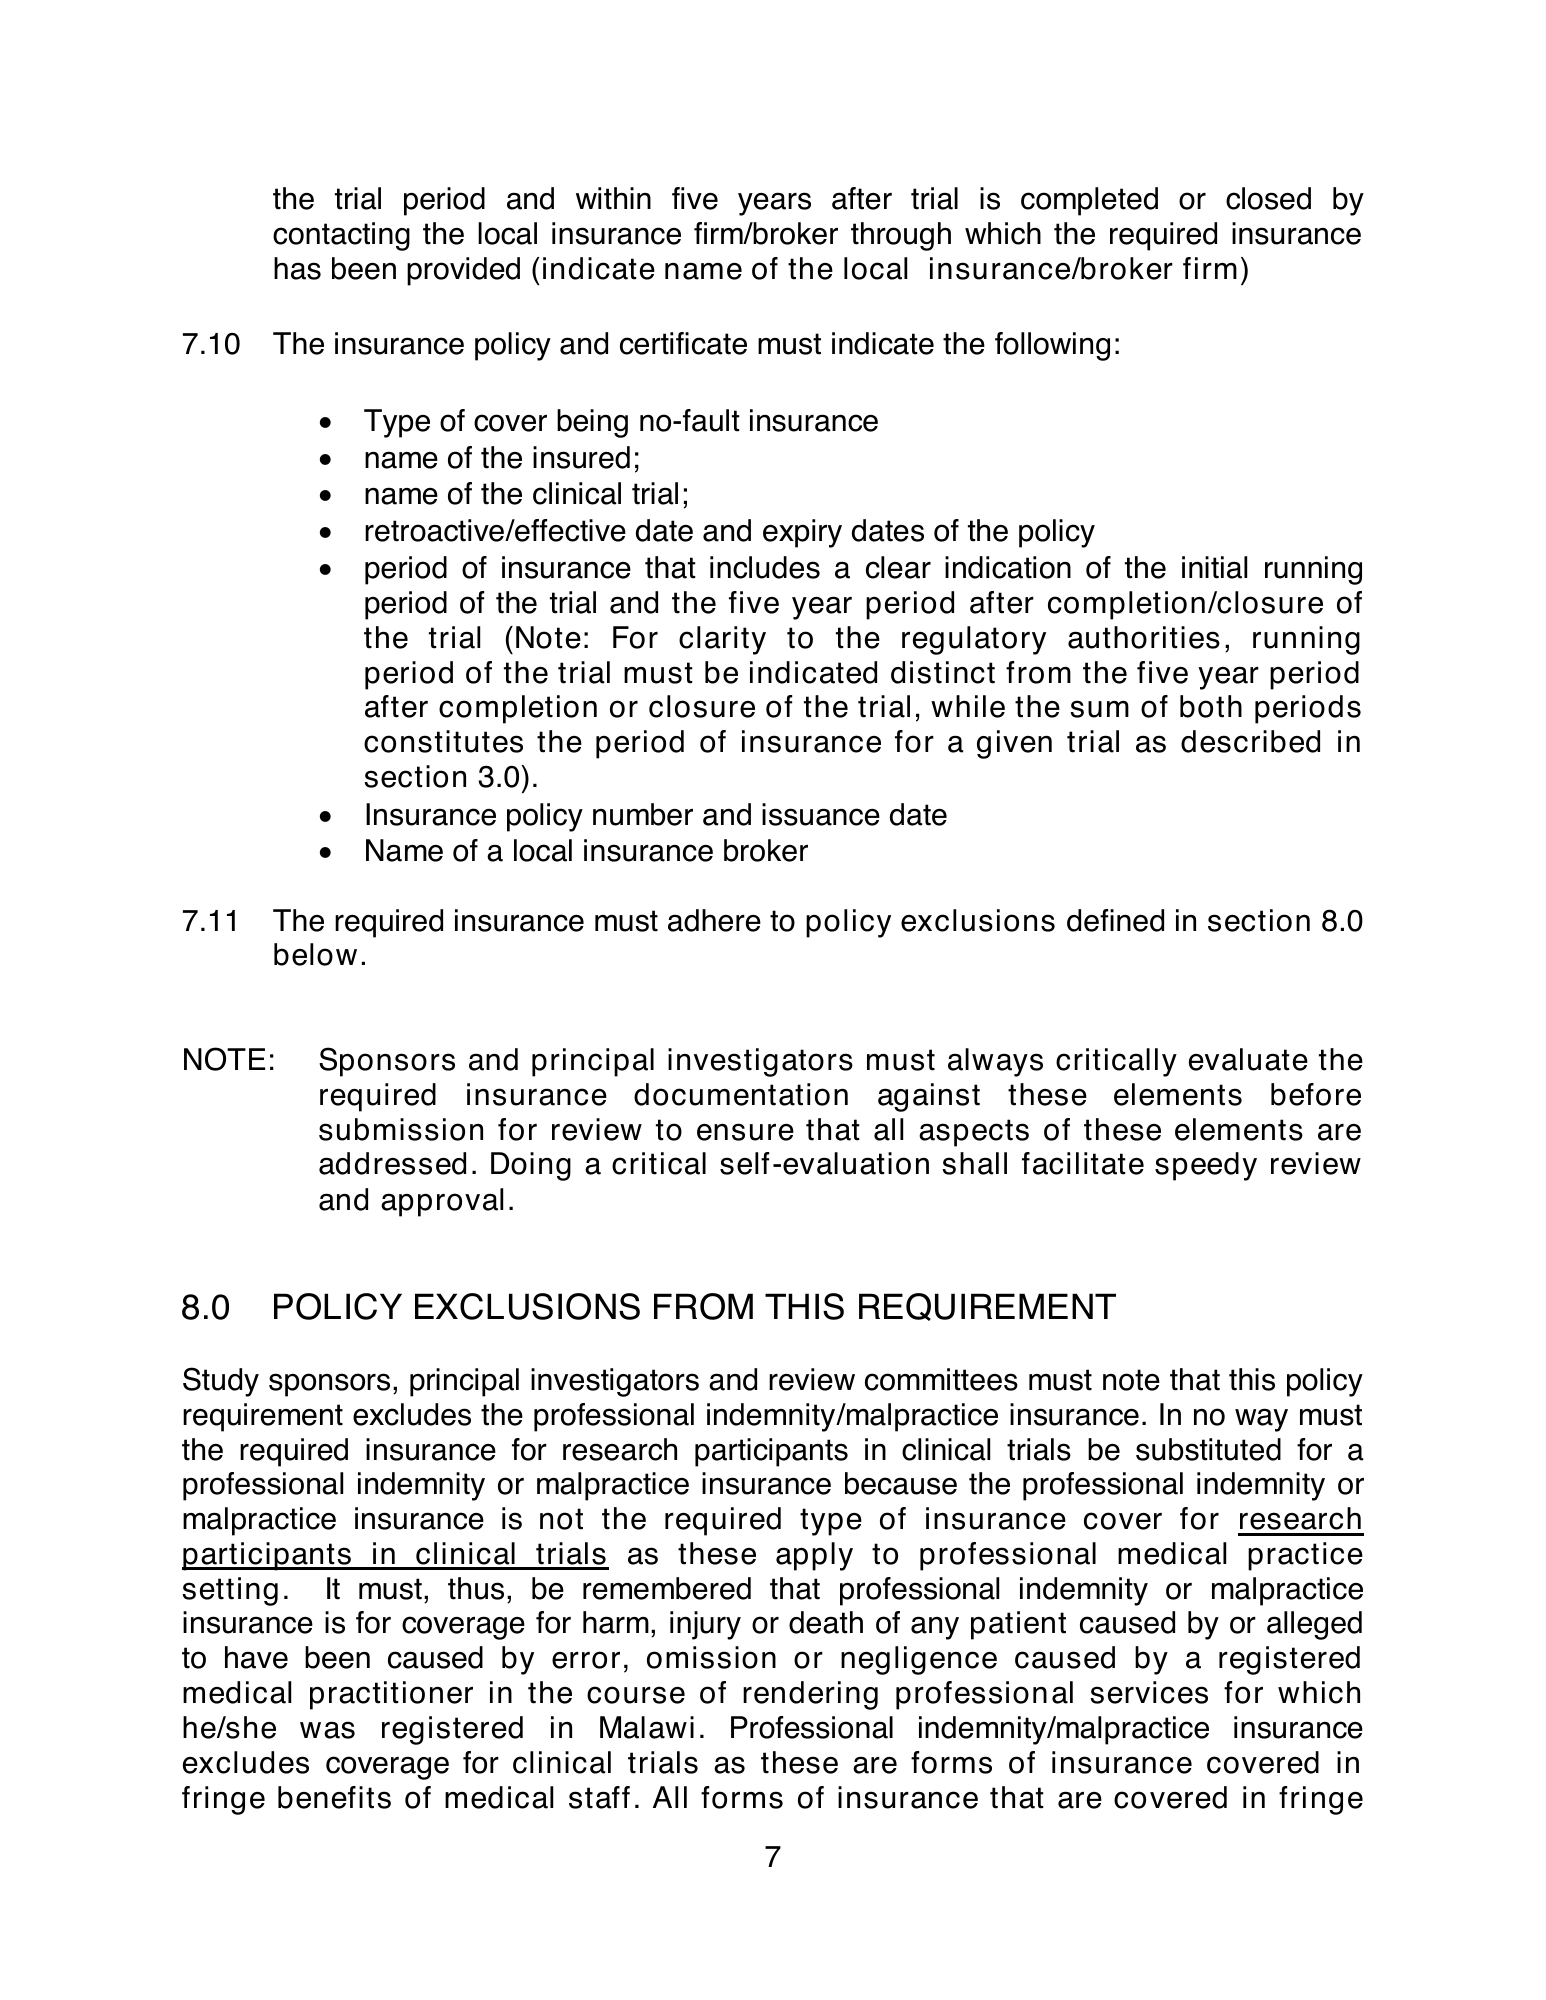
the trial period and within five years after trial is completed or closed by
contacting the local insurance firm/broker through which the required insurance
has been provided (indicate name of the local insurance/broker firm)
7.10 The insurance policy and certificate must indicate the following:
• Type of cover being no-fault insurance
• name of the insured;
• name of the clinical trial;
• retroactive/effective date and expiry dates of the policy
• period of insurance that includes a clear indication of the initial running
period of the trial and the five year period after completion/closure of
the trial (Note: For clarity to the regulatory authorities, running
period of the trial must be indicated distinct from the five year period
after completion or closure of the trial, while the sum of both periods
constitutes the period of insurance for a given trial as described in
section 3.0).
• Insurance policy number and issuance date
• Name of a local insurance broker
7.11 The required insurance must adhere to policy exclusions defined in section 8.0
below.
NOTE: Sponsors and principal investigators must always critically evaluate the
required insurance documentation against these elements before
submission for review to ensure that all aspects of these elements are
addressed. Doing a critical self-evaluation shall facilitate speedy review
and approval.
8.0 POLICY EXCLUSIONS FROM THIS REQUIREMENT
Study sponsors, principal investigators and review committees must note that this policy
requirement excludes the professional indemnity/malpractice insurance. In no way must
the required insurance for research participants in clinical trials be substituted for a
professional indemnity or malpractice insurance because the professional indemnity or
malpractice insurance is not the required type of insurance cover for research
participants in clinical trials as these apply to professional medical practice
setting. It must, thus, be remembered that professional indemnity or malpractice
insurance is for coverage for harm, injury or death of any patient caused by or alleged
to have been caused by error, omission or negligence caused by a registered
medical practitioner in the course of rendering professional services for which
he/she was registered in Malawi. Professional indemnity/malpractice insurance
excludes coverage for clinical trials as these are forms of insurance covered in
fringe benefits of medical staff. All forms of insurance that are covered in fringe
7
malawi-clinical-trial-insurance-policy-2012 — official PDF page 11; original table columns, symbols and diagram connections
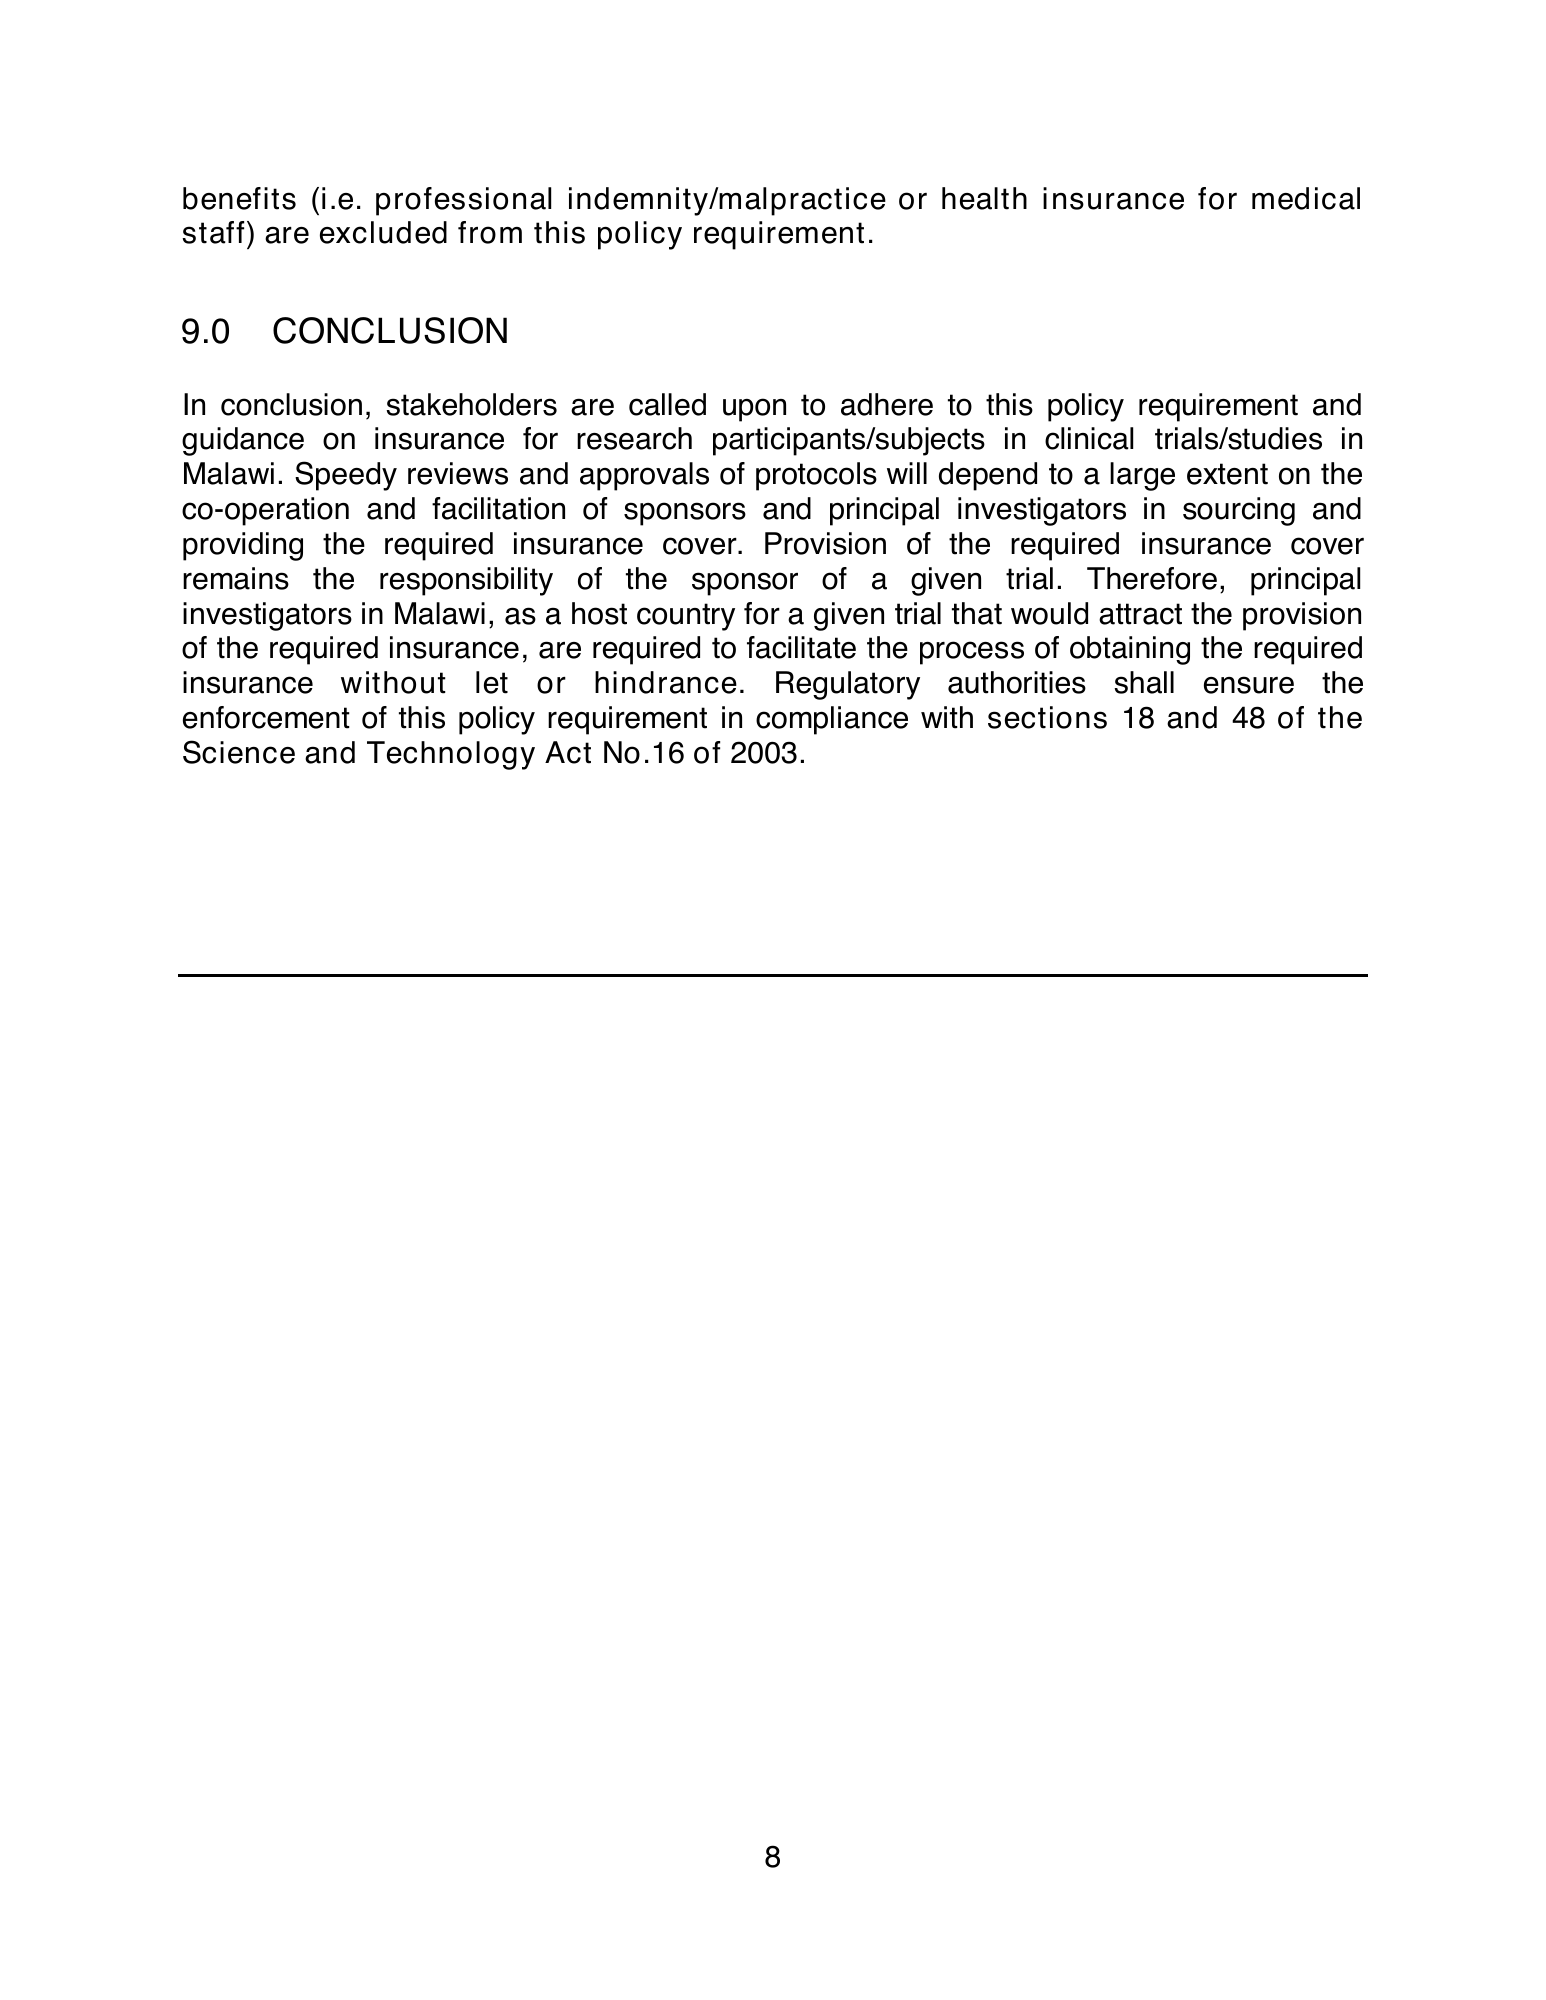
benefits (i.e. professional indemnity/malpractice or health insurance for medical
staff) are excluded from this policy requirement.
9.0 CONCLUSION
In conclusion, stakeholders are called upon to adhere to this policy requirement and
guidance on insurance for research participants/subjects in clinical trials/studies in
Malawi. Speedy reviews and approvals of protocols will depend to a large extent on the
co-operation and facilitation of sponsors and principal investigators in sourcing and
providing the required insurance cover. Provision of the required insurance cover
remains the responsibility of the sponsor of a given trial. Therefore, principal
investigators in Malawi, as a host country for a given trial that would attract the provision
of the required insurance, are required to facilitate the process of obtaining the required
insurance without let or hindrance. Regulatory authorities shall ensure the
enforcement of this policy requirement in compliance with sections 18 and 48 of the
Science and Technology Act No.16 of 2003.
8
malawi-clinical-trial-insurance-policy-2012 — official PDF page 12; original table columns, symbols and diagram connections